Lisa McCann, PhD, RFC®, MS, MA
Principal and Wealth Advisor Seva Wealth Management lisa.mccann@seva-wealth.com
 720-985-8930


September 2026 Market Commentary
Stocks Rebound, The Test Waits
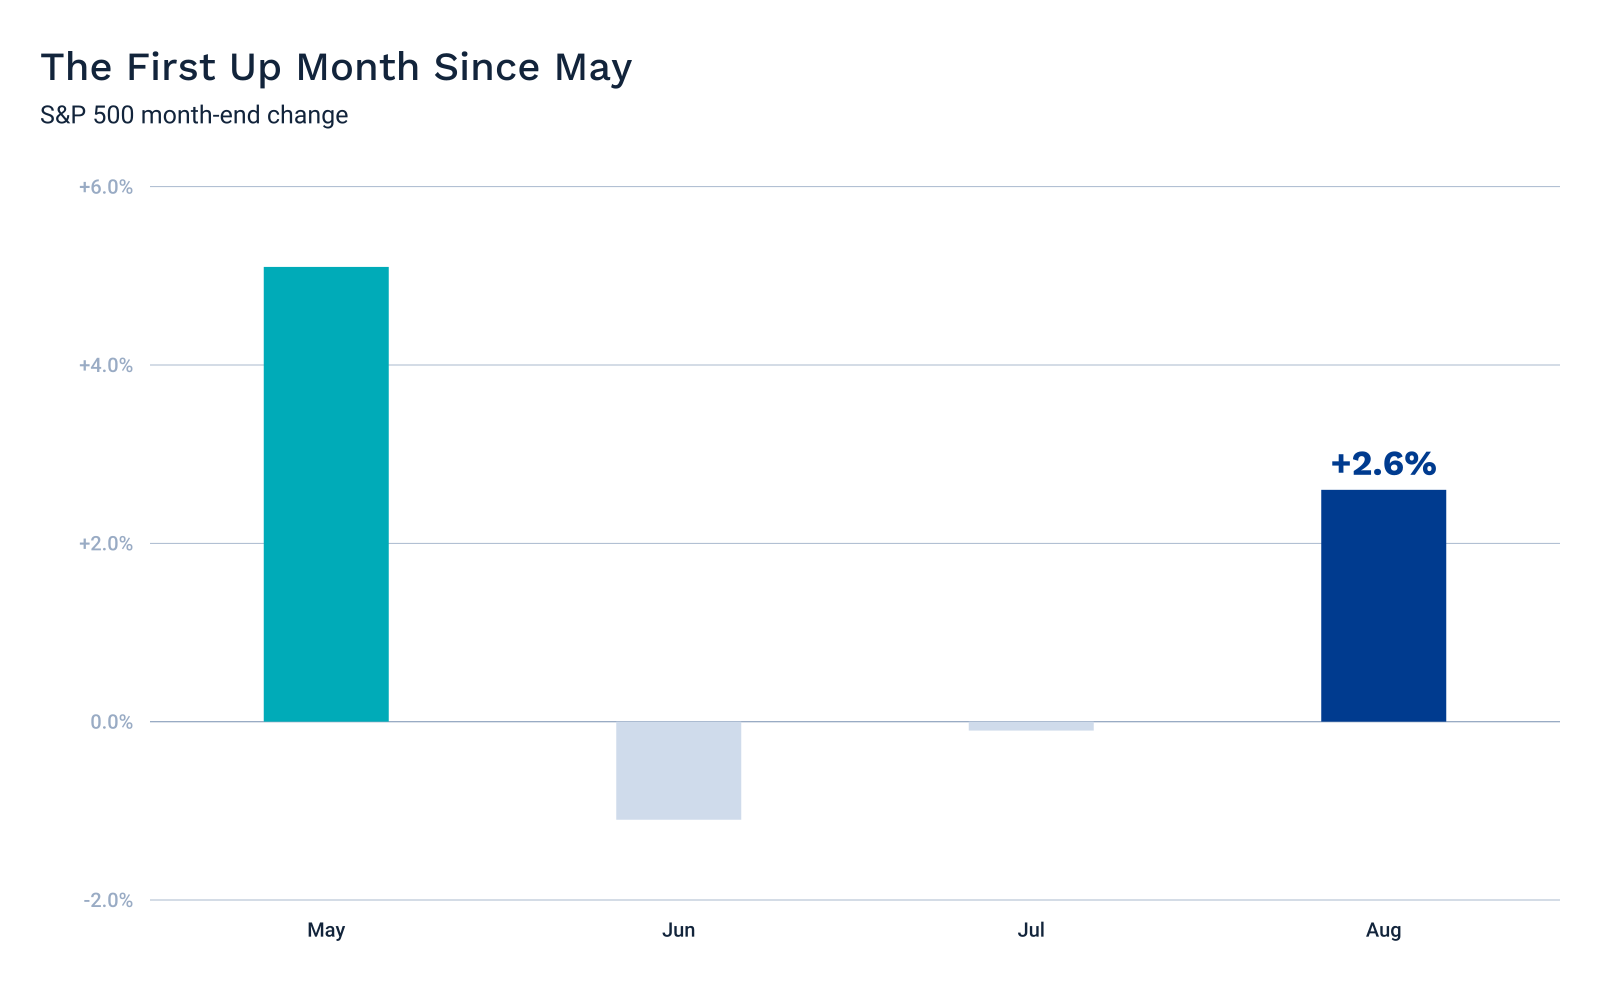
July left two stories on the table: a split equity tape under a nearly unchanged S&P 500, and a war in the Strait of Hormuz that had already pushed crude well above its June low. August answered only the first of those. The S&P 500 closed the month at 7,686.14, 196 points above July's 7,489.72. The Nasdaq Composite finished at 26,370.89. The Dow Jones Industrial Average ended at 53,185.90. It was the first up month for the S&P 500 since May.
The second story did not close. On August 12 the Bureau of Labor Statistics reported that July consumer prices rose 0.1% on the month and 3.4% over the year, with the energy index falling 1.5%. That print was measured before August's flare in the strait. On August 30, Reuters reported, a U.S. official said U.S. forces struck two Iranian launchers on Larak Island after observing preparations to put sea mines into the waterway: the first known American strikes on Iran since late July. Iran responded against U.S. forces stationed in Jordan.
Two days earlier, at Jackson Hole, Fed Chair Kevin Warsh had told the Kansas City Fed's symposium that this summer's CPI and PCE readings "do not tell me that underlying trends have meaningfully improved," and that "we have work to do" unless underlying inflation is moving toward the 2% objective at sufficient speed. CME FedWatch, as reported by CNBC, put the odds of a 25-basis-point hike at the September 15-16 meeting at 66.1% on August 31. Reuters, citing CME data, had put those odds at 35% before the speech. Equities climbed on a cooler print from July. Rate futures climbed on a speech about what that print does not settle.
Let's get into the data:
- August's labor report had not been published as of September 1. The latest print is still July: payrolls fell by 23,000, unemployment held at 4.1%, and BLS revised May down by 66,000 and June down by 37,000.
- July CPI cooled on energy, which is why it cannot speak for August. Headline prices rose 0.1% on the month and 3.4% over the year, down from 3.5%. Core rose 0.2% and 2.5% over the year. Energy fell 1.5% on the month, 14.7% higher than a year earlier. The August CPI release is scheduled for September 11.
- Markets priced a September hike the Chair did not announce. CME FedWatch showed a 66.1% chance of a move at the September 15-16 meeting as of August 31, after Reuters had cited 35% before Jackson Hole. The funds target stayed at 3.50% to 3.75%. Warsh's close was "a discipline, not a decision."
- Growth slowed in the books and ran hotter in the nowcast. BEA's second estimate, released August 26, held second-quarter GDP at a 1.5% annual rate, down from 2.1%. Private domestic final sales rose 4.2%. Atlanta Fed GDPNow stood at 4.6% for the third quarter as of August 26.
What Does the Data Add Up To?
The July CPI report did what a lagging monthly print can do: it closed a chapter. Energy falling 1.5% in July, after a 0.4% decline in the all-items index in June, is the first oil shock washing through the price data. Chair Warsh still called the 12-month PCE change of 3.7%, and the six-month change of 4.1%, "more concerning" than the labor side of the mandate, and said he would be "hard pressed" to describe broad financial conditions as restrictive. Those are statements about the trend. They are not a verdict on one month's energy dip.
The live channel in August ran through Hormuz, not through the CPI table. West Texas Intermediate, which had slumped to $70.56 a barrel at the end of June and then jumped to $86.16 at the end of July, was $83.90 as of August 25, the last FRED observation of the month. That is not a return to the June trough. The Larak strike on August 30 sits after that oil print, which is why the CPI in hand and the oil in the water are not the same test. The chain is direct: a renewed minelaying threat in the strait keeps crude far above its June low, and that is the commodity backdrop Warsh said "bears watching."
Stocks did not wait for the next print. The S&P 500's 196-point August rise was the first monthly gain since May. The VIX closed August 28 at 14.43. High-yield option-adjusted spreads tightened to 2.60% by August 28 from 2.85% at the end of July. That is a market treating last month's cooler inflation as still in force. Fed funds futures treating a September hike as the more likely outcome, at 66.1% on August 31, is a market treating it as stale. As of September 1, August payrolls and August CPI had not been published. Warsh said in the speech that a majority of the July FOMC preferred to await new information in the intermeeting period. That information was still incoming when the calendar month ended.
Chart of the Month: The First Up Month Since May
The S&P 500's month-end change flipped from two down months to a gain in August. The rebound is a price. It is not the August inflation print, which had not been released when the month closed.
Equity Markets in August
The S&P 500 gained 196.42 points, or 2.62%, to finish August at 7,686.14. The Nasdaq Composite rose 997.04 points, or 3.93%, to 26,370.89. The Dow Jones Industrial Average added 700.87 points, or 1.34%, to end at 53,185.90. All three major indexes advanced for the month, even after falling on August 31 as renewed U.S.-Iran hostilities pushed oil prices higher.
Bond Markets in August
The 10-year Treasury yield ended August at approximately 4.75%, essentially unchanged from its July 31 level. The 30-year Treasury yield finished near 5.25%, down slightly from 5.27% at the end of July. Long-term yields nevertheless moved sharply higher on August 31 as rising oil prices renewed concerns about inflation and the possibility of another Federal Reserve rate increase.
The Smart Investor
A green month on the statement is easy to file as things getting better. The distinction that matters is the calendar, not the mood. The inflation number in the August conversation is a July number, measured before the month's strike in the strait. The stock rebound is an August price. Those two facts can sit together without either one being a verdict on the oil shock.
If the headlines feel as if they are arguing with each other, that is a reason to walk the plan, the time horizon, and the cash needs with us rather than to pick a winner between last month's CPI and this month's index close. We're always here to answer your questions and provide support.
Sources
Federal Reserve Bank of St. Louis (FRED) - S&P 500, Nasdaq Composite, Dow Jones Industrial Average, WTI crude, federal funds target range, VIX, ICE BofA high-yield OAS, 10-year and 30-year Treasury yields. fred.stlouisfed.org
U.S. Bureau of Labor Statistics - Consumer Price Index, July 2026 (as of 2026-08-12). bls.gov
Reuters - U.S. forces struck two Iranian launchers on Larak Island (as of 2026-08-30). reuters.com
Federal Reserve - Chairman Warsh Jackson Hole remarks, August 28 2026 (as of 2026-08-28). federalreserve.gov
CNBC, citing CME Group FedWatch - September FOMC hike probability 66.1% (as of 2026-08-31). cnbc.com
Reuters, citing CME data - September hike probability 35% before the Jackson Hole speech and 60% as it landed (as of 2026-08-28). reuters.com
U.S. Bureau of Labor Statistics - The Employment Situation, July 2026 (as of 2026-08-07). bls.gov
U.S. Bureau of Economic Analysis - GDP second estimate, 2nd quarter 2026 (as of 2026-08-26). bea.gov
Federal Reserve Bank of Atlanta - GDPNow nowcast for 2026 Q3 (as of 2026-08-26). atlantafed.org
Morningstar - iShares Core U.S. Aggregate Bond ETF July 2026 return (as of 2026-07-31). morningstar.com
This work is powered by Advisor I/O under the Terms of Service and may be a derivative of the original.
The information contained herein is intended to be used for educational purposes only and is not exhaustive. Diversification and/or any strategy that may be discussed does not guarantee against investment losses but are intended to help manage risk and return. If applicable, historical discussions and/or opinions are not predictive of future events. The content is presented in good faith and has been drawn from sources believed to be reliable. The content is not intended to be legal, tax or financial advice. Please consult a legal, tax or financial professional for information specific to your individual situation.
This content not reviewed by FINRA
Disclosure information
The opinions expressed in this article are for general informational purposes only and are not intended to provide specific advice or recommendations for any individual. Nothing contained herein constitutes investment, financial, legal, or tax advice, nor should it be relied upon as such. Past performance is not indicative of future results. All investing involves risk. Seva Wealth Management provides advisory services to clients or prospective clients only where appropriate registration and licensing has been completed, and in the context of comprehensive financial planning. Please contact us at www.Seva.Wealth.com, Lisa.McCann@Seva-Wealth.com, or 720-985-8930 to explore financial planning and discuss how this information may apply to your personal financial circumstances. Schedule a meeting today!